
Physical Gift Proofs: Sample Courier Budget and Approval Dates
Tie each physical proof to one approval decision, one shipment owner and a confirmed courier offer. Use an internal decision cutoff to see when a repeat proof would change the event plan.
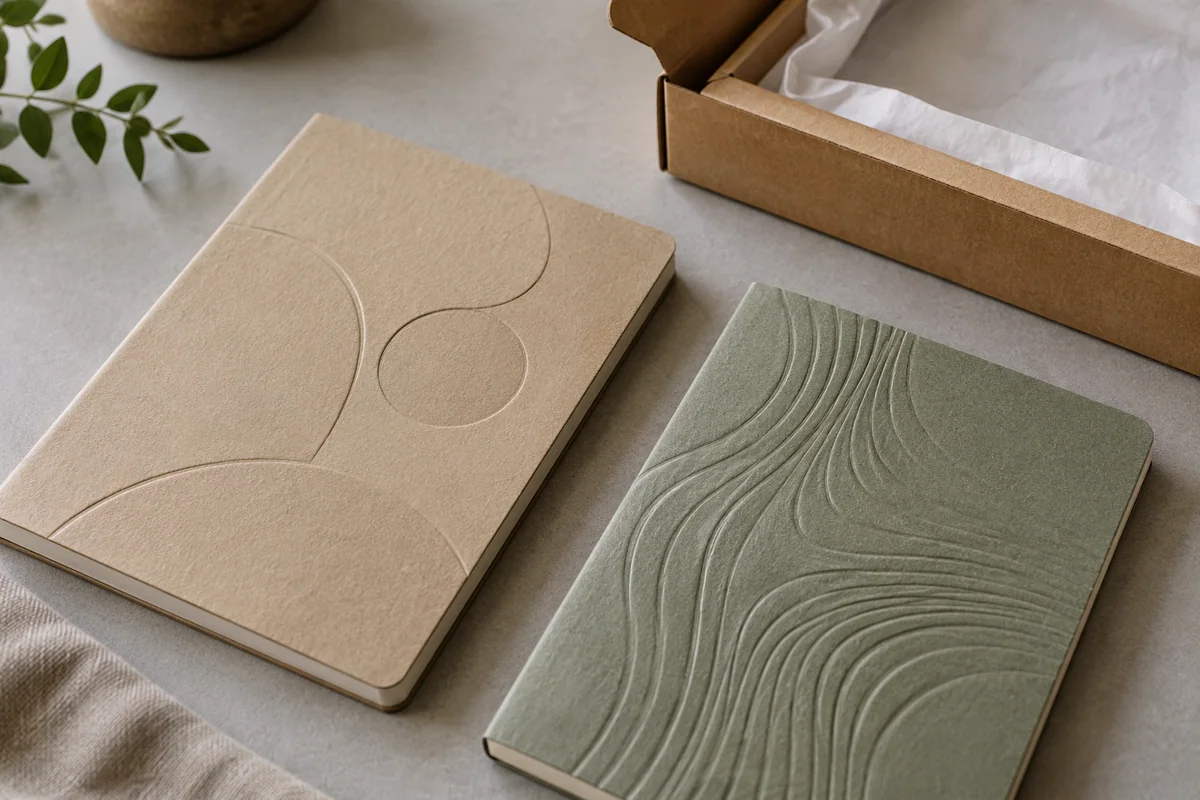
Budget a physical gift proof by the decision it must enable, then authorise its dispatch separately from any possible repeat. A reserve for a revised notebook sample is useful planning money; it is not a standing instruction to send successive parcels until somebody says stop.
The practical question is how many distinct physical approval rounds the proposed custom gift needs, who can close each round and which shipment costs have actually been approved. Start with the agreed product, decoration brief and recipient-group requirement. This is a courier-spending decision, not a new set of technical acceptance limits or a way to predict bulk freight from a sample bill.
Give each proof round one decision
Write the unresolved buying question before asking for a parcel. For a notebook gift, it might be whether the identified physical cover and proposed decoration deliver the agreed appearance for the campaign. Refer to the existing specification and its decision criteria; do not invent impression depth, durability thresholds or a different approved artwork area to fill the register.
Identify the physical object that will answer the question: notebook model, cover revision, artwork issue and disclosed substitutions. A sample made on a different cover may still inform a discussion, but its dispatch should not be described as closing the exact production-intent question unless the responsible owner accepts that limitation.
A digital artwork approval cannot establish the physical finish of the delivered proof. Conversely, sending another physical notebook is not automatically useful when the remaining decision is only which already approved message to use. Ask the decision owner what evidence is missing and whether another physical dispatch is necessary for that specific gap.
The custom gift-printing guide covers broader sample and production approval gates. Keep those technical decisions attached to the correct proof, while this register controls the cost of getting the required evidence to its reviewer.
Separate the evidence plan from the shipping instruction
Name the person who will review the proof and the person who can authorise its courier cost. They may be the same person, but record both roles. Confirm the intended destination and the scope of that journey before asking for an actual offer. Use group or role references in the working budget rather than circulating a recipient list.
Distinguish sample manufacture, decoration setup, protective packing, outbound carriage, return carriage and any onward transfer to another reviewer. Ask which items the proposed amount covers. If a supplier provides one bundled total, preserve the bundle’s written scope instead of labelling the whole figure “courier.”
Record the proof-ready condition as well as the proposed dispatch. An artwork file being approved does not establish that the physical notebook is made, checked or available for collection. Equally, a parcel being handed over does not show that the reviewer received it or approved the relevant finish.
Use a proof-round shipping authorisation register
These rows describe a fictional plan. They authorise no real dispatch, service, sample or deadline.
| Proof purpose | Required physical evidence | Decision owner | Dispatch allowance | Repeat trigger | Approved ceiling |
|---|---|---|---|---|---|
| Initial notebook appearance decision | Identified proposed notebook proof with substitutions disclosed | Named campaign reviewer | 45 CU reserved for one outbound dispatch | Reviewer identifies a change requiring new physical evidence | Initial dispatch only after scope approval |
| Possible revised-proof decision | Revised notebook reference answering the recorded exception | Same reviewer or expressly appointed replacement | Additional 45 CU held conditionally | Written revised-proof requirement and new dispatch approval | 90 CU combined reserve for the two assumed outbound rounds |
Add actual quotation references, the date of the spending decision, amount committed and amount spent alongside the register when those facts exist. Keep “reserved,” “authorised,” “committed” and “spent” distinct. An unspent allowance can still be committed under agreed commercial terms, so do not release it merely because no invoice has appeared.
Define a repeat trigger narrowly. “Buyer changes the approved cover finish and requests a new physical proof” identifies a decision. “Sample not approved” is too vague: it does not say whether the issue needs a new physical object, who pays or whether another dispatch is permitted.
Work the reserve without inventing expenditure
All amounts here are fictional currency units, abbreviated CU, not courier rates or supplier fees. The imagined plan reserves 45 CU for one outbound notebook proof and 45 CU for a possible revised proof:
45 CU + 45 CU = 90 CU maximum reserved for those two outbound journeys.
If the first dispatch actually costs the assumed 45 CU and no revised proof is needed, the illustrative expenditure is 45 CU. The other 45 CU remains an unused reserve until the budget owner confirms it is uncommitted and releases or reallocates it. The presence of a 90 CU reserve does not mean 90 CU was necessarily spent.
If a revised proof is required, first confirm why it is needed, who bears the charge and what the revised dispatch covers. The example does not establish a right to a free correction, a credit against the bulk order or a fixed proof duration. A higher real quotation or a changed journey needs a fresh spending decision rather than silent use of another budget line.
The reserve excludes sample manufacture, artwork or tooling charges, any return journey, onward review journey, duties, taxes and unlisted handling. No equality with those costs is assumed. It is a limited proof-dispatch provision, not complete sampling cost or landed cost for the gifts.
Decide who sees the object and in what sequence
A brand reviewer and an event owner may need different evidence from the same proof. Ask whether the agreed review can happen at one destination or requires an onward journey. Do not assume either co-location or an available forwarding service.
If the buyer proposes sending separate proofs to multiple reviewers, record that as changed sample and dispatch scope before requesting approval. If it proposes sequential review, identify the handover owner and any return requirement. The cheaper-looking plan is incomplete while an essential review journey has no payer or agreed method.
Record the actual event need, the provider’s proposed proof milestones and the buyer’s next decision point. These are planning inputs, not promised transit times. If review cannot be completed before the buyer’s decision point, the owner must choose what changes; an additional courier payment does not itself establish date readiness.
Close a round with the decision, not the parcel status
For each round, retain the proof identity, dispatch evidence, receipt confirmation, review finding, responsible person and next decision. A useful exception says what remains unresolved and whether it requires another physical proof. Agree an update cadence for the engagement rather than assuming continuous tracking or an automated approval portal.
When the required review is complete, close only the relevant proof-dispatch budget. Production approval and the bulk shipment retain their own evidence and authorisations. The gift shipping-cost guide supplies the separate wider transport foundation.
For a gift quote enquiry, describe the approved notebook configuration, the physical question to be resolved, the reviewer destination and the requested scope for initial and possible revised dispatches. Ask for each actual charge and any credit terms in writing before treating an allowance as an offer.
Worked decision register: first proof, revision and event cutoff
For a fictional event plan, the buyer sets an internal artwork and sample decision cutoff eight days before the event. The deadline is a buyer planning assumption. Ask the supplier for verified proof readiness, the courier for pickup and delivery assumptions, and the production team whether the remaining window meets the approved plan.
The first courier leg is budgeted at CNY 80. A new physical proof is provisionally reserved at CNY 90 only if the first sample’s color or placement changes. If the buyer accepts the first sample and the quoted dispatch is paid at 80, the remaining 90 stays uncommitted. Record who approved the revision, the next decision date and any fees associated with a change.
| Gate | Evidence to obtain | Budget or next decision |
|---|---|---|
| First physical proof | Actual SKU, artwork revision, print and packout photos | 80 for the first dispatch, subject to its written quote |
| Repeat proof | Reason for revision, changed evidence and revised ready date | 90 reserved only if approved |
| Event minus 8 days | Buyer decision cutoff and actual confirmed remaining schedule | Approve, switch to an available fallback, or hold production |
Frequently asked questions
How many physical gift-proof rounds should I budget for?
Start with the unresolved physical decisions and ask which sample can answer each. Reserve for a repeat only where a meaningful revision could require new physical evidence. The fictional two-round plan is a teaching example, not a universal requirement, supplier entitlement or recommendation to repeat every sample.
Does a 90 CU reserve mean both courier journeys are approved?
No. The example reserves 45 CU for an initial outbound proof and another 45 CU conditionally. Each dispatch needs its stated scope and spending authority. Record commitments separately from expenditure, and release an unused reserve only after checking that no related charge remains committed.
What changes if the approved gift or recipient group changes?
Recheck whether the existing proof still answers the physical decision for the revised configuration and intended group. Identify the evidence gap before commissioning another object. A revised review location or additional reviewer may also change dispatch scope, even when the physical proof itself remains suitable.
What should be confirmed before paying to send a revised proof?
Keep the original finding, requested change, revised proof reference, reviewer, journey scope and payer together. Confirm sample-making and courier charges separately, including any return or credit arrangement. No waived fee, arrival date or physical approval follows from a general promise to make a correction.
Discuss a sourcing request related to this article.Physical Gift Proofs: Sample Courier Budget and Approval Dates